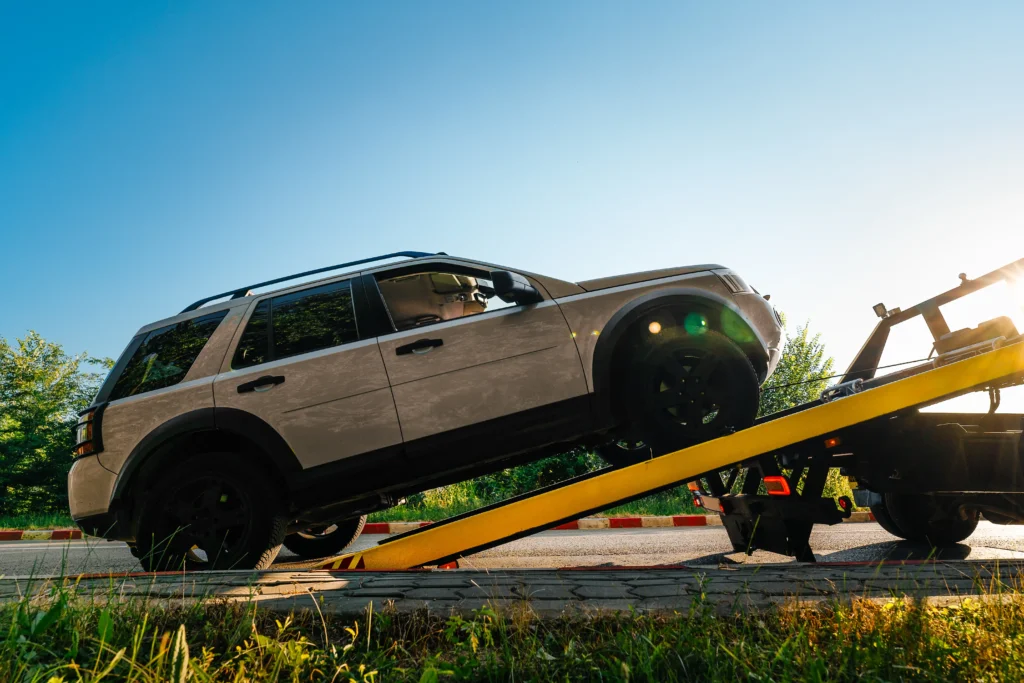
If your car was repossessed in Texas, the loan usually does not end there. The lender can sell the car, and if the sale brings in less than you owed plus allowed costs, the difference is a deficiency balance that the lender may try to collect, including by filing a lawsuit. Texas law puts a time limit on that lawsuit, and Chapter 7 and Chapter 13 bankruptcy each deal with a deficiency balance in their own way.
This guide covers what happens after the tow truck leaves, how a deficiency is calculated, what the time limit means, and where bankruptcy fits. If your car has not been taken yet, start with our post on whether bankruptcy can stop car repossession in Texas.
What Happens After a Car Is Repossessed in Texas?
After a repossession, the lender generally either keeps the vehicle to cover the debt or sells it. The Federal Trade Commission explains that you may be able to buy the car back by paying the full amount you owe, which typically includes past-due payments, the entire remaining debt and repossession costs, or by bidding on it at the repossession sale. Some states also let a borrower reinstate the loan by paying the past-due amount plus the lender’s repossession expenses.
Watch your mail closely in the weeks after a repossession. Lenders often send notices about the planned sale, and those notices can matter later if there is a dispute about the balance. Keep every letter, envelope and statement together in one folder.
Your personal belongings
Things you left inside the car are not part of the collateral. According to the FTC’s guide to vehicle repossession, a lender cannot keep or sell personal property found in a repossessed vehicle at least until a certain amount of time has passed, and in some states the lender has to tell you what it found and how to get it back. Contact the lender or the repossession company as soon as you can and ask how to collect your things.
What Is a Deficiency Balance?
A deficiency is the difference between what you owed on the contract, plus certain expenses, and what the lender received when it sold the car. Costs tied to the repossession and the sale can be added to the balance, so the amount left over is often larger than people expect.
The FTC notes that in most states a lender can sue for a deficiency judgment, as long as it followed the rules for repossession and sale. In the less common case where the car sells for more than you owe, including the lender’s expenses, the extra is called a surplus, and the lender might be required to pay it to you.
Questions to ask about the balance
- Did you receive a notice before the car was sold, and when did it arrive?
- What did the car sell for, and which fees were added to the balance?
- Is the original lender collecting, or has the account been sold to a debt buyer?
- When did you make your last payment?
Your answers help an attorney see whether the balance looks right and which options make sense for you.
Is There a Statute of Limitations on a Repossession Deficiency in Texas?
There is a time limit on lawsuits. The Texas State Law Library explains that Texas law gives a creditor four years to bring a lawsuit for unpaid debt. Once that period is up, the debt is “time-barred.” You still owe it, but the creditor loses its most powerful way of collecting: a lawsuit.
Two details matter. First, when the four years begin depends on the facts of your account, so the date of the repossession or the sale is not automatically the starting point. Second, the Law Library notes that under Section 392.307 of the Texas Finance Code, a payment or other activity on the debt does not restart the clock for debt buyers. The rules for an original lender can be different, so do not assume a small payment is harmless before you get advice.
A time limit on lawsuits is not the same as the debt going away. Calls and letters can continue. If you are close to the limit, or past it, an attorney can explain what that means for you.
What If the Lender Sues You for the Deficiency?
A deficiency lawsuit is filed in a Texas state court. Do not ignore the papers. Missing the deadline to respond can lead to a default judgment, and a judgment gives the creditor more ways to collect.
J. Brian Allen does not practice law in Texas state courts. What he can do is explain whether filing bankruptcy in federal court is the better route. Filing a bankruptcy case puts the automatic stay in place, stopping most collection activity, including most pending collection lawsuits. Some actions may still proceed in limited circumstances. Our post on how bankruptcy stops a debt lawsuit explains the timing in more detail.
How Chapter 7 Treats a Deficiency Balance
Once the car has been sold, the lender no longer has the vehicle as collateral, so the remaining deficiency is generally treated like other unsecured debt in a bankruptcy case. Chapter 7 can give you a fresh start by wiping out qualifying unsecured debts. A discharge means the legal obligation to pay the discharged debts is eliminated, and creditors covered by the discharge cannot legally require payment on those debts.
Whether Chapter 7 fits depends on your income, household and expenses. A court-appointed trustee reviews the case, and exemptions may allow you to keep essential property. You can learn more on our Chapter 7 bankruptcy page.
How Chapter 13 Treats a Deficiency Balance
Chapter 13 is a court-approved repayment plan that runs for several years. A deficiency balance is usually grouped with your other unsecured debts in the plan. Depending on your budget, those creditors may receive part of what they are owed, and remaining eligible unsecured balances can be discharged when the plan is completed.
Chapter 13 can make sense when you have other goals at the same time, such as catching up on a home loan or protecting property, or when Chapter 7 is not available to you. Read more on our Chapter 13 bankruptcy page.
Steps to Take Now
- Gather your paperwork: the loan contract, every notice from the lender, and any sale or deficiency letter.
- Write down the key dates: your last payment, the repossession and any sale date you were given.
- Arrange to get your personal belongings out of the vehicle.
- Open every envelope from a court or a law firm. Response deadlines in a lawsuit are short.
- Get advice before paying, or promising to pay, an old balance.
- Look at the whole picture. A deficiency often arrives alongside other debts, which is when a bankruptcy review is most useful.
Frequently Asked Questions
Can a lender come after me for money after it repossesses my car?
Often, yes. If the sale does not cover what you owed plus allowed costs, the lender may try to collect the deficiency and may sue for it, as long as it followed the rules for repossession and sale.
How long does a lender have to sue for a deficiency in Texas?
The Texas State Law Library states that Texas law gives four years to bring a lawsuit for unpaid debt. When that period starts depends on your account, so have the dates reviewed rather than counting from the repossession.
Should I pay the deficiency balance?
It depends on the amount, your other debts and where you are in the time limit. Paying can be the right choice for some people, but get advice first, especially if the account has been sold or the balance is old.
Can bankruptcy wipe out a deficiency balance?
A deficiency is usually treated as unsecured debt. In Chapter 7, qualifying unsecured debts can be discharged. In Chapter 13, the balance is usually handled through the plan, and remaining eligible unsecured balances can be discharged when the plan is completed.
Talk With a Bankruptcy Attorney in Sulphur Springs
When you hire J. Brian Allen, he is your attorney. The initial consultation is free, by phone or online, and appointments are required. Call (903) 439-5150 or request a consultation. The office is at 430 Church Street, Suite 2, Sulphur Springs.
J. Brian Allen is licensed in Oklahoma and admitted to the U.S. District Courts and U.S. Bankruptcy Courts for the Eastern and Northern Districts of Texas. He does not practice law in Texas state courts. This page is informational and not legal advice. Results depend on your facts and the law that applies to your case. J. Brian Allen is a debt relief agency.